Connecting global capital with energy projects in emerging economies

Global Energy Bridge brings market intelligence, local understanding and relevant relationships to connect capital providers with energy projects and the companies equipped to deliver them. Power grid infrastructure is our principal focus.

Our focus: power grid infrastructure
One integrated approach to bringing power where it is needed most.

We examine opportunities across generation, transmission, distribution, storage and system integration. Our role is to understand the need, clarify the opportunity and connect relevant capital providers with project companies and expertise.

Generation

Matching supply to real community demand.We evaluate local energy resources against actual load profiles and daily power needs. The focus is on selecting practical, cost-effective tech options that lower energy costs and ensure a dependable long-term supply.

Transmission

Bridging the gap between generation and local users.We ensure power moves reliably from solar fields or power units directly to the local distribution hubs serving the community.

Distribution

Delivering power directly to consumers and businesses.A grid is only as strong as its reach. We plan local distribution lines, household connections, and smart metering to ensure quality service, minimize line losses, and maintain a sustainable operating model.

Storage

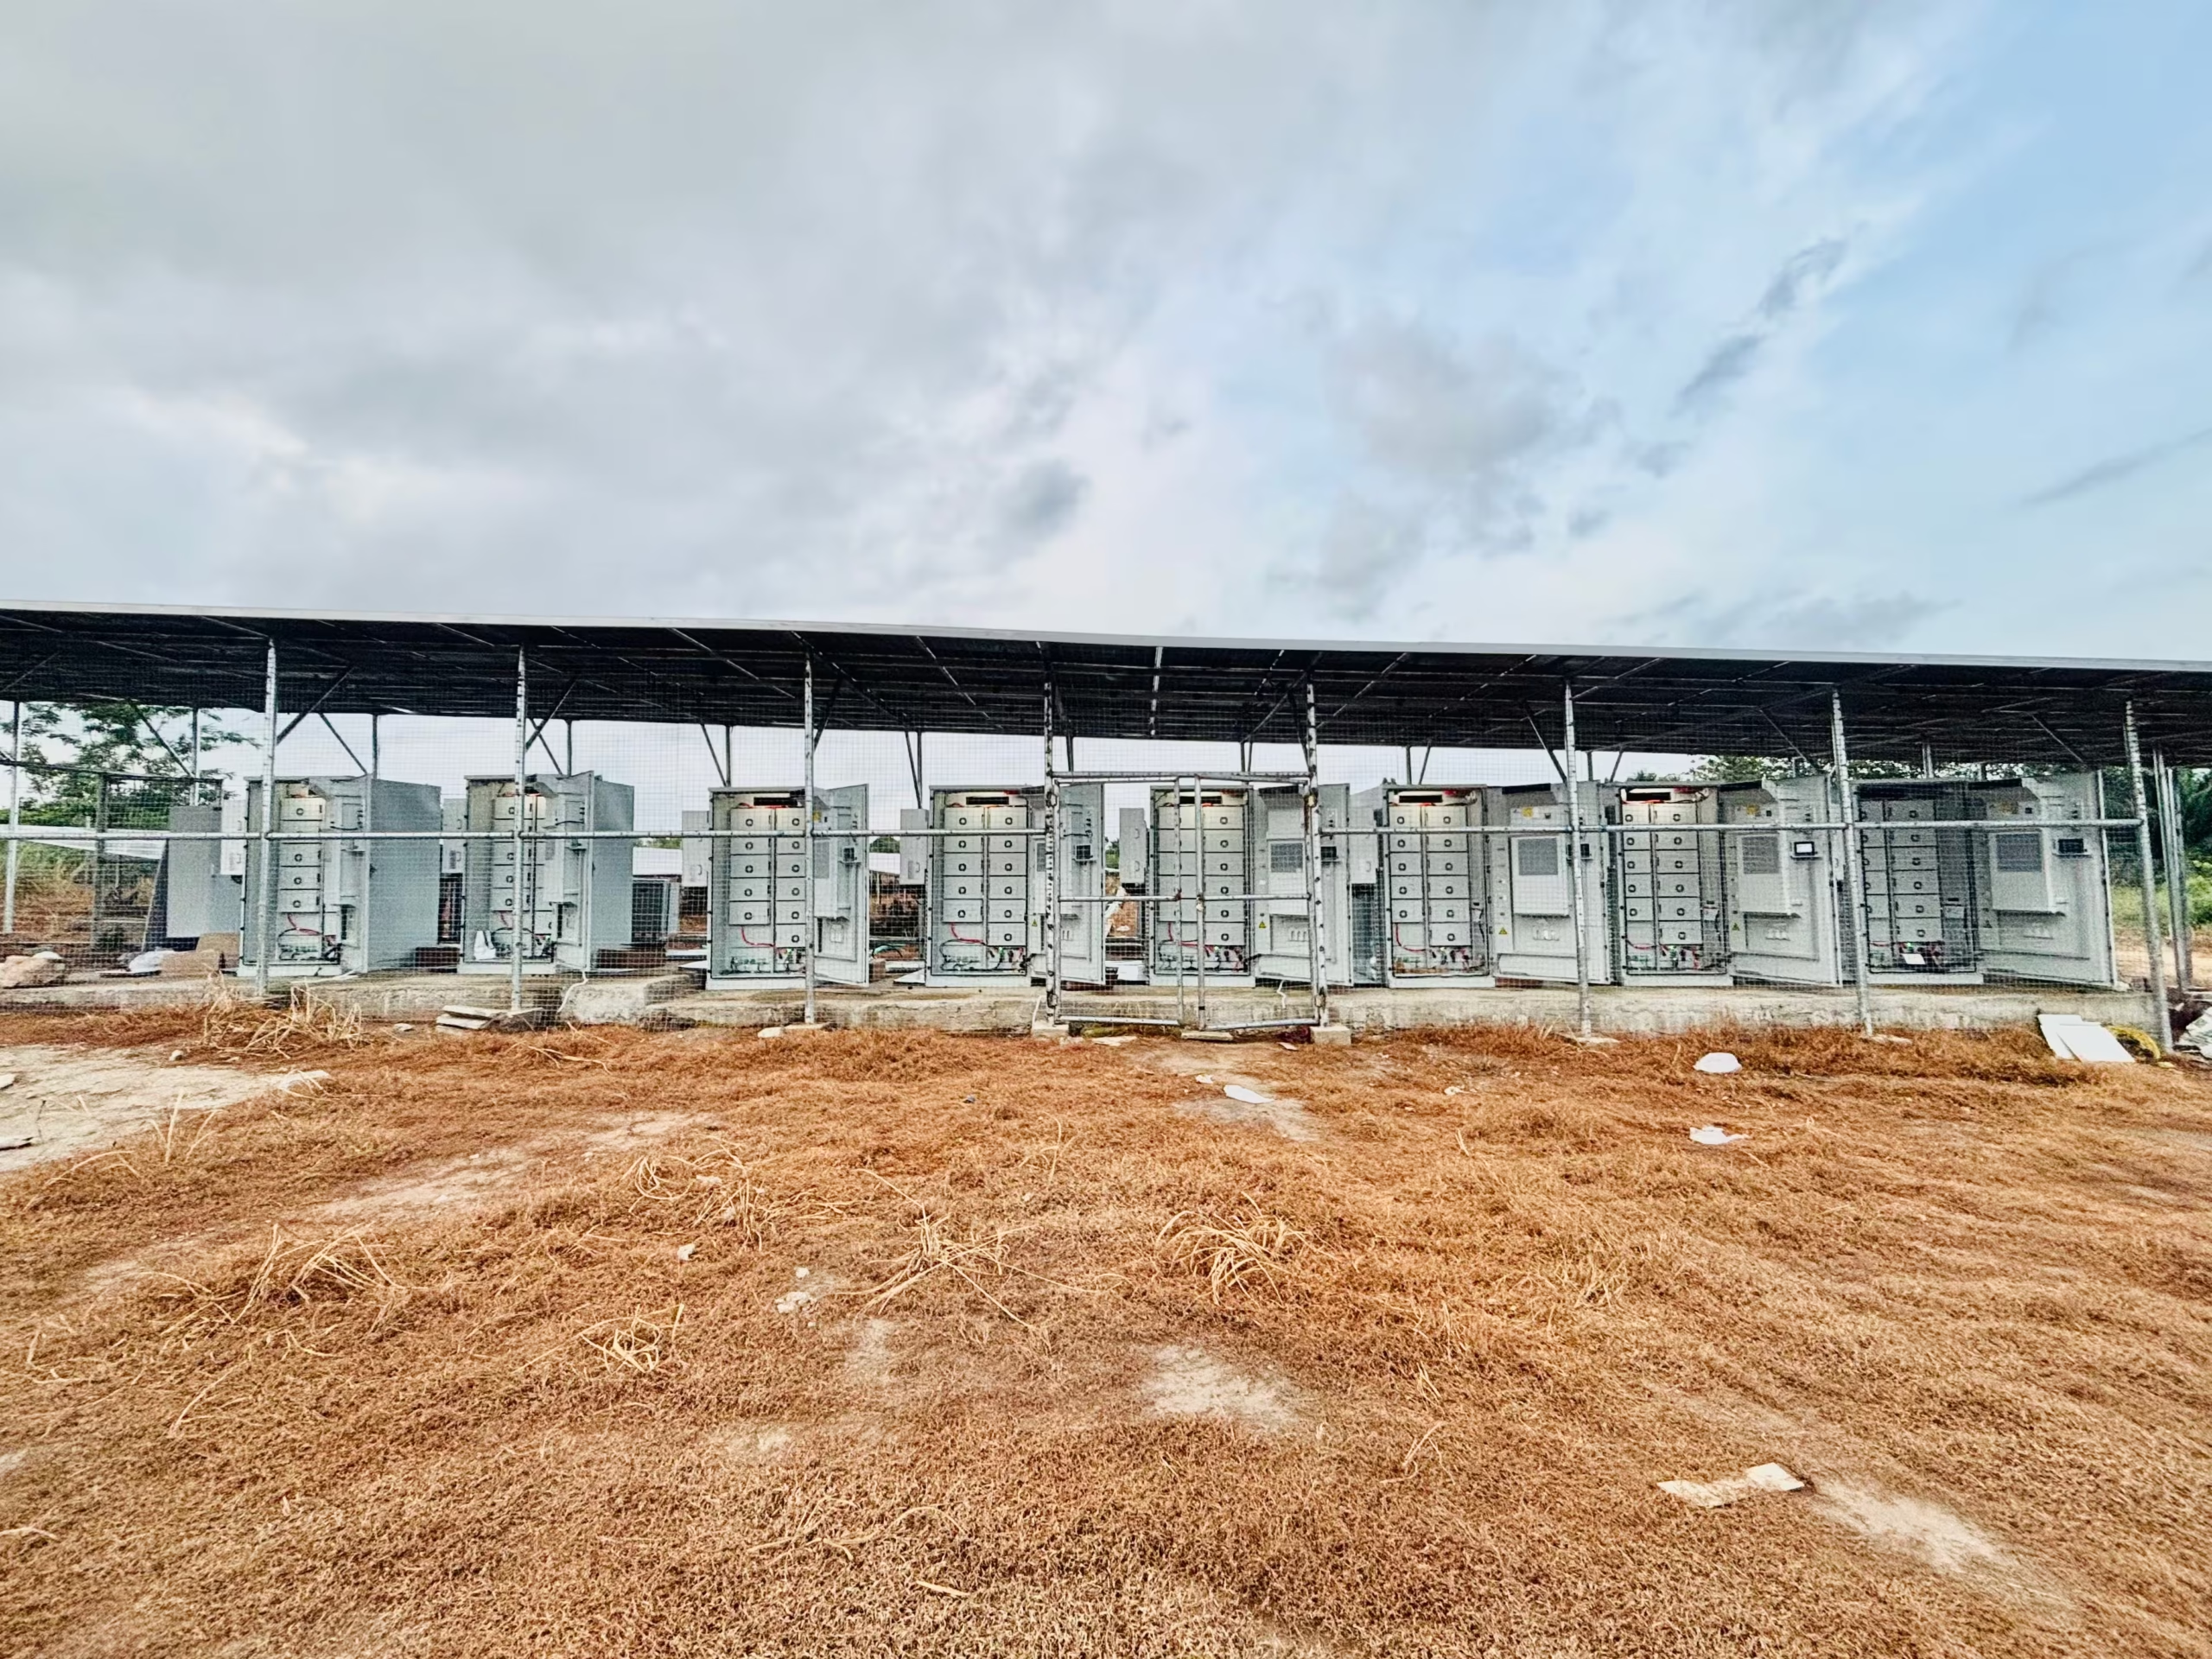
Keeping the lights on when conditions shift.Solar and wind are variable, but critical services can't stop. We integrate battery storage and backup systems so hospitals, businesses, and communities enjoy stable, uninterrupted power around the clock.

Global Energy Bridge connects energy projects with relevant capital and execution expertise. We bring market intelligence, knowledge of the local terrain and relationships that help participants assess opportunities with meaningful development impact.

Connecting Capital, Expertise and Impact

Global Energy Bridge coordinates project preparation for mini-grids and local power networks, starting in Nigeria. Each engagement defines the development work required, the responsibilities of project partners and the evidence needed for the next decision.

Define demand and the service area

We coordinate assessment of the proposed customer group, load profiles, existing supply and required service levels. This establishes the basis for comparing supply options and testing demand assumptions.

Assess the technical and commercial model

We coordinate technical and commercial inputs to assess generation, local distribution and, where appropriate, storage and grid interconnection. The assessment considers lifecycle costs, tariffs or customer contracts, metering, collections and operating responsibilities.

Map approvals and development requirements

We coordinate engagement with relevant authorities, network owners, landholders and community representatives. The development workplan identifies approvals, land rights, environmental and social assessments, and specialist studies required for the proposed project.

Prepare for financing and implementation

We organise project information, partner responsibilities and outstanding development tasks for independent investor and lender assessment. Where appointed, we coordinate interfaces between project partners through the agreed implementation stages.

Clear responsibilities at each stageGEB's coordination role is defined in the agreed engagement. Appointed project partners are responsible for engineering, construction, financing and operation. Financing remains subject to independent due diligence and approval by the relevant capital providers.
Discuss a Project

Better infrastructure decisions start with understanding the market.

Explore country-level electricity indicators and market context to inform initial project screening. National data provides a starting point; mini-grid development requires local assessment of consumer demand, network conditions, regulatory requirements and commercial viability.

54Countries in the geographic index
563 millionPeople without access to electricity in Sub-Saharan Africa in 2024
2030SDG 7 target year for universal access to electricity

Electricity-access data: Tracking SDG 7, 2026 edition; reference year 2024.

Click any country
Hover to identify · click for intelligence
Preparing the Africa map…The country boundaries will appear here shortly.

Algeria Energy Intelligence Profile

Population
~47.4M
Supplied estimate · 2025 attribution
Installed capacity
30.5–32.7 GW
Supplied range · reference year pending
Electricity access
99.7–100%
Supplied range · reference year pending
Reported generation
~95 TWh
Annual output · reference year pending

Country Overview & Demographics

Capital

Algiers

Region

North Africa , Middle East and North Africa (MENA)

Language(s)

Arabic is the official language, with Tamazight (Berber) as a national and official language, and French widely used in commerce, higher education, and administration.

Geography

A major North African nation bordered by the Mediterranean Sea to the north, Tunisia and Libya to the east, Niger, Mali, and Mauritania to the south, and Western Sahara and Morocco to the west, featuring a dominant Saharan desert interior and a narrow fertile northern coastal strip (the Tell Atlas).

Currency

Algerian Dinar (DZD).

Population & Demography

~47.4 million inhabitants (World Bank 2025) featuring a growing, youth-skewed demographic base.

Population Breakdown by Age

Children aged 0–14 account for approximately 29%, the working-age population (15–64 years) represents roughly 65%, and seniors aged 65 and older comprise about 6%.

Median Age & Youth Structure

A moderate median age of roughly 28.6 to 28.8 years, with a substantial portion of the population under 25 driving domestic consumption and workforce expansion.

Workforce Breakdown

A labor force heavily concentrated in public administration, hydrocarbon extraction and processing, services, agriculture, and an expanding industrial and manufacturing base.

Urbanization Rate & Velocity

Highly urbanized at approximately 74.4% to 74.8%, with populations heavily clustered in major northern metropolitan hubs including Algiers, Oran, Constantine, and Sétif.

Power Baseline & Generation Capacity

Installed vs. Available Generation Capacity

Total grid-connected installed capacity is approximately 30.5 to 32.7 GW, providing robust generation assets managed primarily by the state utility.

Reported Generation

Annual electricity generation reaches approximately 95 TWh to satisfy national industrial and residential demands.

Renewable Output

Renewable sources account for approximately 1% to 4% of total output, though rapidly scaling under aggressive national clean energy programs.

Power Needed

Suppressed or unmet demand is minimal due to near-universal electrification, with total consumption tracking closely alongside generation capacity. Research note: this assessment requires a dated source or a defined measurement; it is not a verified score or risk conclusion.

Supply Shortage

Negligible baseline supply deficit, as total installed capacity comfortably exceeds peak operational demand. Research note: this assessment requires a dated source or a defined measurement; it is not a verified score or risk conclusion.

Prevailing Energy Mix

Heavily dominated by natural gas-fired thermal power plants, accounting for over 97% of total generation capacity, with minor shares contributed by hydroelectric and solar photovoltaic installations.

Electrification & Infrastructure Reality

Electricity Access

Near-universal national electrification rate standing at approximately 99.7% to 100%, reflecting extensive long-term government rural and urban connectivity programs.

Rural vs. Urban Electrification Split

Exceptional parity between urban and rural connectivity, with remote areas systematically integrated through national grid extensions managed by Sonelgaz. Research note: this assessment requires a dated source or a defined measurement; it is not a verified score or risk conclusion.

Peak Demand vs. Supply

Peak electricity demand reached approximately 19.1 GW against an installed capacity exceeding 32 GW, maintaining a healthy reserve margin.

Grid Reliability Index

High reliability backed by an extensive high-voltage transmission and distribution network spanning close to 100% of the national territory. Research note: this assessment requires a dated source or a defined measurement; it is not a verified score or risk conclusion.

Primary Constraint Summary

The core structural challenge is not a lack of power capacity, but rather the heavy domestic consumption of natural gas for power generation, which eats into valuable hydrocarbon export revenues and drives the urgent necessity to pivot toward large-scale renewables.

Financial, Economic & Investment Environment

Sovereign Credit Rating (Moody’s, S&P, Fitch)

Sovereign credit profile sits at BB (Stable) with a solid macroeconomic standing underpinned by hydrocarbon wealth. Research note: this assessment requires a dated source or a defined measurement; it is not a verified score or risk conclusion.

Foreign Exchange Liquidity & Import Cover Ratio

Robust foreign exchange reserves providing a strong import cover ratio exceeding 14 to 16 months.

World Bank B-READY / Regulatory Climate Score

Benchmarked under robust state-led industrial frameworks, featuring strong institutional control and centralized public enterprise operations. Research note: this assessment requires a dated source or a defined measurement; it is not a verified score or risk conclusion.

World Economic Forum Energy Transition Index (ETI) Score

Reflects high system performance in terms of universal energy access, while actively transitioning toward lower-carbon baseload configurations. Research note: this assessment requires a dated source or a defined measurement; it is not a verified score or risk conclusion.

Capital & Currency Environment

Tightly regulated foreign exchange and capital repatriation regime managed by the Bank of Algeria, requiring state-aligned partnership structures and sovereign guarantees for major infrastructure.

Offtaker Risk & Utility Financial Health

Exceptionally low offtaker default risk, as the power sector is centralized and vertically integrated under Sonelgaz, the state-owned national electricity and gas company. Research note: this assessment requires a dated source or a defined measurement; it is not a verified score or risk conclusion.

Aggregate Technical, Commercial, and Collection Loss Rate

Low technical and commercial loss ratios compared to regional peers, sustained by strict metering, high grid integrity, and centralized collection. Research note: this assessment requires a dated source or a defined measurement; it is not a verified score or risk conclusion.

Tariff Cost-Reflectivity Status

Regulated retail electricity tariffs managed by the Commission for Energy and Gas Regulation (CREG), heavily cushioned by state subsidies to ensure affordability across residential sectors.

Regulatory & Project Landscape

IPP Regulatory Framework

Governed by CREG under national electricity laws. While historically dominated by state utilities, recent legislative adjustments and massive competitive solar tenders (such as multi-gigawatt PV programs) are increasingly opening doors for Independent Power Producers (IPPs) and Build-Own-Operate (BOO) models.

AfDB Electricity Regulatory Index Score

High regulatory maturity score reflecting advanced administrative frameworks, clear licensing procedures, and structured tariff methodologies across North Africa. Research note: this assessment requires a dated source or a defined measurement; it is not a verified score or risk conclusion.

Captive & Off-Grid Legal Allowance

Permitted and increasingly encouraged under regulatory frameworks for remote industrial zones, mining operations, and agricultural irrigation (such as Sonelgaz's mass connection of rural farms).

Active Project & Tender Pipeline

Massive national renewable targets aiming for 15 GW of solar capacity, backed by consecutive multi-gigawatt solar tenders (including major 3 GW and 3.2 GW deployment phases) and nascent green hydrogen export corridors.

Actionable Entry Points

Utility-scale solar photovoltaic engineering, procurement, and construction (EPC), supply of high-voltage grid equipment, industrial captive solar installations, and technology partnerships for green hydrogen and green ammonia export projects.

What this means for participation

Read the opportunity through fuel substitution and delivery capability. If the supplied baseline is confirmed, near-universal access shifts the central question towards replacing domestic gas consumption, serving growing demand and integrating new renewable capacity. A national surplus of installed capacity does not establish spare operating capacity at a particular location.

Separate project models before assessing entry. Solar EPC, equipment supply, industrial captive generation and independent power production involve different buyers, permissions, revenue structures and responsibilities. A public tender for construction should not be assumed to offer an IPP or BOO investment route.

Test the commercial conditions behind each project. Procurement eligibility, payment security, foreign exchange access, repatriation arrangements, grid connection, land rights and local delivery capacity need transaction-specific evidence. State ownership alone does not establish low counterparty risk.

Treat targets as direction, then establish status. Renewable and hydrogen ambitions can guide further enquiry, but project announcements need to be distinguished from awarded contracts, construction, commissioning and operating assets. These are GEB’s analytical observations, not additional country statistics.

Energy Intelligence Profile

Country intelligence preview

Country

Loading current comparable indicators…

Evidence statusRetrieving source data…
Capital—Country profile
Population—Latest available
RegionAfricaGeographic classification
Electricity access—Latest available
Reported generation—World Bank series
Renewable output—Share of electricity output
Power neededModel pendingRequires demand methodology
Supply shortageModel pendingNot inferred from access alone

Power situation and challenge

A verified country brief is being prepared. The available comparable indicators above provide an initial evidence layer, not a complete market assessment.

Political and regulatory lens

Editorial review pending. Political and regulatory conditions require dated, source-led country research and should not be generated automatically.

Predominant power source

Country energy-mix profile in development.

Renewable pathways for assessment

Country assessment pending
Comparable data: World Bank Open Data. Country boundaries are rendered with amCharts geodata. This preview is market orientation, not an investment recommendation.

We make Africa's energy markets easier to understand, enter and act within.

01 / Market intelligence

We show where the need, demand and enabling conditions intersect.

Global Energy Bridge organises country and location evidence to help investors and technical partners identify where further project assessment is justified. We examine electricity access, service reliability, network conditions, economic activity and resource availability, with an initial focus on mini-grids and local power networks in Nigeria.

The review distinguishes electricity need from demand that can sustain a service. Relevant evidence includes consumer load profiles, seasonal activity, existing energy expenditure, affordability and likely connection uptake. National indicators provide context; site surveys and local data are needed to establish the conditions within a proposed service area. Sources, reference periods and assumptions remain visible in the assessment.

This work supports a location screening brief identifying potential consumer groups, constraints and gaps in the evidence. Investors can use it to decide which locations warrant site investigation and technical and commercial feasibility work.

Nigeria as a focal point

Nigeria is our initial development focus. We assess opportunities for mini-grids and local power networks through consumer demand, existing electricity service, network conditions and the applicable regulatory framework. Project preparation brings these factors together within a defined service area.

36 + FCTjurisdictions6geopolitical zones1 atlasstate energy overview

Explore Nigeria by state. Click or tap a state on the map to open its energy profile. You can also choose a state from the list below. Use the search and filters to narrow the map.

37 areas shown · Select a state or the FCT to open its profile.

Interactive map of NigeriaClick or tap a state to open its profile ↗Hover to see state names. Keyboard: Tab, then Enter.
Or choose a state below

Every state name opens an energy profile.

No state matches those filters. Clear a filter and try again.

Population figures: NBS/NPC 2019 projections, published in the NBS Demographic Bulletin.

Your interest in Africa's energy market should begin with the right questions.

Tell us what you are seeking to fund, develop, deploy or understand. Global Energy Bridge will use your objectives, preferred markets, technology interests, investment range and risk considerations to frame a more relevant starting point for engagement.

Start an investor needs analysis Speak with our team